Harper Albrecht · 30 October 2026
Shifts in Harvesting Calendars Among Remote Timber Suppliers Reshaping Supply Chains for Luthiers Seeking Consistent Tonewoods
Remote timber suppliers in mountainous and boreal regions have adjusted traditional harvesting windows over recent years, and these modifications now influence how tonewoods reach luthiers who build stringed instruments. Data collected through forestry monitoring programs shows that seasonal access periods for species such as Sitka spruce and curly maple have shifted by several weeks in multiple sourcing zones since 2023. Suppliers cite altered precipitation patterns and earlier snowmelt as primary factors driving the new calendars, while regulatory agencies require updated permits tied to these environmental records.
Documented Changes in Harvest Timing
Forestry records from western North America and parts of northern Europe indicate that cutting seasons for high-grade resonance woods once ran from late spring through early autumn; yet many operations now extend or compress these intervals depending on ground conditions. A report released in October 2026 by Natural Resources Canada outlined how certain British Columbia districts moved allowable harvest dates forward by an average of eighteen days compared with 2018 baselines. Similar adjustments appear in Scandinavian supply areas where state forest services track snow-free periods more closely each decade. These calendar shifts affect log extraction volumes because crews must complete work before soil saturation or protected wildlife windows close access routes.
Supply Chain Ripple Effects for Instrument Makers
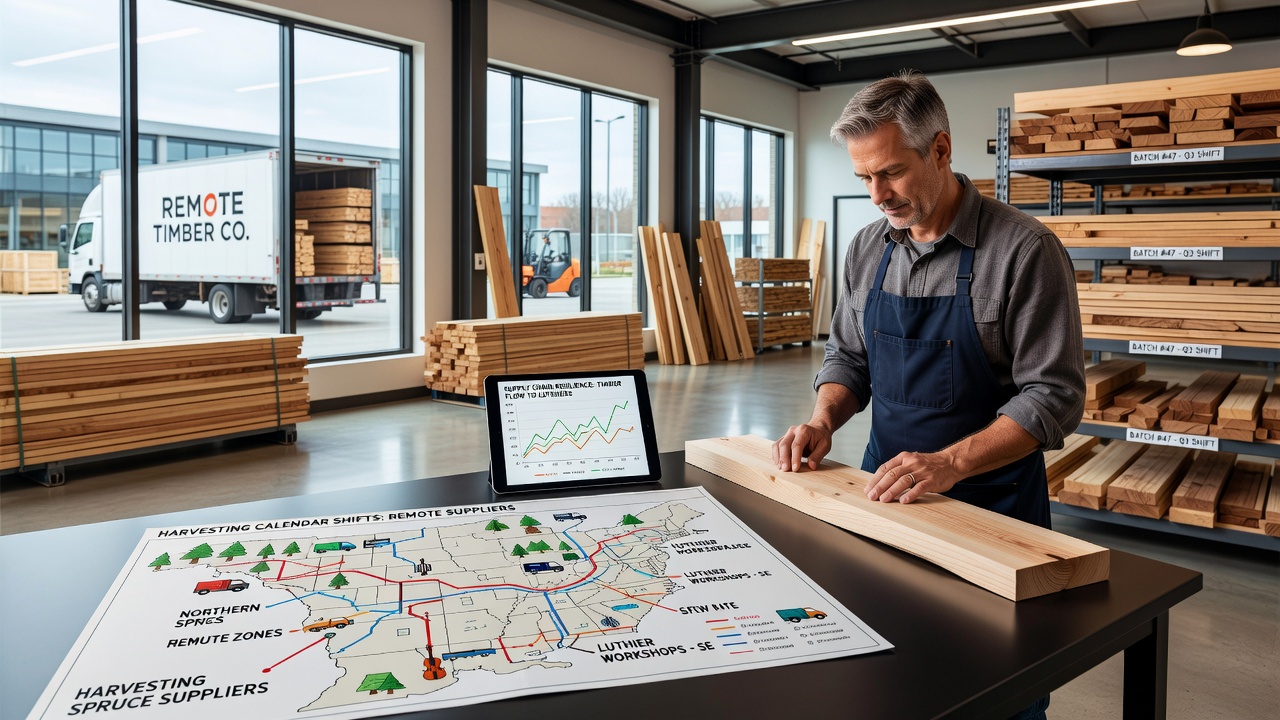
Luthiers who rely on steady deliveries of quarter-sawn blanks encounter longer lead times when suppliers hold inventory until the revised harvest windows close. Distributors report that tonewood lots previously arriving in workshops by November now often reach North American and European buyers in January or February. One mid-sized tonewood broker based in Oregon noted that container shipments from coastal Alaska arrived twenty-six days later in 2025 than in 2021, forcing several custom builders to reorder alternative lots or delay instrument completions. Inventory buffers at specialty mills have increased accordingly, and some facilities now maintain two-season stockpiles to smooth delivery gaps. The reality is that luthiers working on limited runs must coordinate orders earlier in the year or accept wood from secondary regions when primary sources experience delays.
Adaptations Among Remote Suppliers and Downstream Buyers
Suppliers operating in isolated zones have introduced staggered cutting crews and additional storage yards closer to roads that remain passable longer into the wet season. Equipment upgrades such as low-impact forwarders allow operations to continue under marginal conditions that previously halted work. Meanwhile, luthiers and small mills have expanded relationships with multiple sourcing regions; some now source Sitka spruce from both Alaska and British Columbia within the same build season to offset single-area shortfalls. Research from the University of British Columbia Faculty of Forestry tracks these multi-region strategies and finds that shops maintaining three or more supplier contracts experienced fewer production interruptions during the 2024-2025 transition period. Certification programs that verify chain-of-custody documentation have also updated audit cycles to reflect the new harvest calendars, requiring extra paperwork for each lot that crosses seasonal boundaries.
Observers note that smaller remote operations face higher compliance costs when permits must be renewed against revised environmental calendars. Larger suppliers absorb these expenses more readily and sometimes consolidate volumes from several small cutters before shipping. This consolidation concentrates availability at fewer distribution points, which in turn influences pricing structures for quartersawn billets that luthiers select for top plates and backs. Figures released by the International Tropical Timber Organization in late 2025 showed a modest rise in average per-board-foot costs for certified resonance woods moving through consolidated channels compared with direct small-supplier purchases.
Regional Examples and Ongoing Monitoring
In the Carpathian Mountains, Romanian forest districts adjusted beech and maple harvest windows by roughly twelve days earlier in response to spring flooding records compiled through 2025. European luthiers who source these woods reported receiving shipments in batches that no longer align with traditional winter drying schedules, prompting some workshops to install additional climate-controlled storage. Across the Pacific Northwest, data from the U.S. Forest Service indicates that certain national forest units now issue harvest authorizations only after soil moisture sensors register below threshold levels, a change implemented in 2024. Luthiers tracking these rules have begun requesting pre-season notifications from suppliers so they can plan tonewood selections around expected arrival windows rather than fixed calendar dates.
What's interesting is how these adjustments interact with existing sustainability certifications; audits now incorporate satellite imagery of snow cover and precipitation to verify that harvesting stayed within permitted seasonal bounds. Mills that once processed logs within weeks of cutting now hold larger volumes in climate-monitored sheds while awaiting transport windows. The ball remains in the court of both suppliers and buyers to coordinate these new timelines effectively.
Conclusion
Harvest calendar modifications among remote timber suppliers continue to influence tonewood availability and delivery timing for luthiers who require consistent material properties. Monitoring programs from government agencies and academic institutions document the extent of these shifts, while supply chain participants respond through diversified sourcing, expanded storage, and adjusted ordering practices. Ongoing data collection through October 2026 and beyond will determine whether these patterns stabilize or require further operational changes across the tonewood distribution network.